Log InSign Up
  • Primary
  • Secondary
  • Cryptolending
  • Token
  • My investments
  • More
    Leagues
    Transactions
    Referral program
    Help & Feedback
    Twitter
    Telegram
    LinkedIn
  • Primary
  • Secondary
  • Cryptolending
  • Token
  • My investments
  • More
Log InSign Up
PrimarySecondaryCryptolendingInvestments
PrimarySecondaryCryptolendingTokenMy investments
LeaguesTransactionsReferral programHelp & Feedback
TwitterTelegramLinkedIn
Trustpilot
  • Terms and Conditions
  • Privacy Policy
  • Help & Feedback
  • WEB2 Platform
🧰 ServicesID: 761

Commercial Construction

0USDC
0% of 20,000 USDC
Risk scoreBBB
Annual interest23.40 %
Term10 months
Expires
Sign up to Invest
Overview
Risk scoring
Financials
Collateral
Borrower
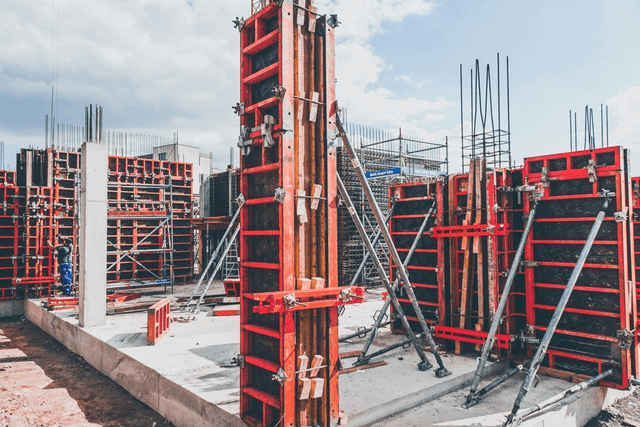
Own equipment for a hybrid execution model

Lutrina is raising €500,000: €415,000 buys machinery and site equipment to self-perform earthworks and concrete works, and €85,000 is a working-capital buffer for peak execution.

0USDC
0% of 20,000 USDC
Risk score: BBB10 months23.40 %
Commercial Construction

Lutrina Construction And General Supplies Limited is a privately owned Kenyan construction company incorporated on 14 March 2018. The company operates primarily in Nairobi and its surrounding metropolitan areas, focusing on small- to mid-scale residential and commercial construction projects.

The company functions as an asset-light general contractor, assuming full responsibility for project coordination, subcontractor management, procurement of construction materials, cost control, quality supervision, and client communication. Physical construction works are executed through a network of specialised subcontractors, while Lutrina retains contractual and execution risk under fixed-price or hybrid (fixed price with approved variations) contracts.

In addition to general contracting services, Lutrina independently procures and supplies construction materials to its project sites. Material sourcing and delivery represent a distinct margin component alongside the general contracting fee, contributing to overall project profitability.

The company is led by its CEO and sole shareholder, Doreen Kendi Mukami, an engineer by training with prior professional experience in large contracting and real estate development organisations in Kenya. Strategic decision-making, pricing discipline, contractor selection, and execution oversight are centralised at management level, reflecting a management-driven operating model rather than asset- or technology-led execution.

Lutrina does not maintain permanent in-house construction crews or heavy equipment. As part of its confirmed development strategy, the company plans to selectively introduce owned construction equipment and transition toward a hybrid execution model, enabling limited self-performance of standardised civil work packages while retaining a subcontractor-led structure.

The company’s target clients include private property developers, landowners, and small commercial investors seeking predictable delivery under a single coordinating contractor. The operating model emphasises flexibility, controlled scaling, and low fixed costs, while relying on disciplined project selection, accurate cost estimation, and effective subcontractor coordination.

Loan Collateral 

The €500,000 loan facility is secured by a combination of loan-financed construction equipment, corporate assets, and personal collateral provided by the owner of Lutrina Construction And General Supplies Limited. The collateral structure is asset-based, transparent, and directly linked to the company’s operating activities.

Collateral Composition

Loan-financed equipment (pledged to the lender)

For collateral valuation purposes, the construction equipment acquired under Tranche 1 is valued on a conservative basis, applying a 15% discount to nominal purchase cost to reflect liquidation assumptions.

Asset category

Nominal value (€)

Discount

Collateral value (€)

Construction machinery and equipment

415,000

15%

352,750

Additional collateral

Asset

Estimated value (€)

Toyota Land Cruiser Prado J150 (2022)

41,500

Corporate reserves

150,000

Total collateral

191,500


Collateral Coverage

Metric

Value (€)

Total collateral value

544,250

Loan principal

500,000

Collateral coverage ratio

108.9%

The pledged assets consist of standard, marketable construction equipment with established secondary-market liquidity, supplemented by liquid corporate reserves and personal collateral. The collateral package fully covers the loan principal and provides an adequate recovery buffer for the lender.

The pledged equipment is integral to the execution of the company’s active and confirmed project portfolio and is expected to remain in continuous operational use throughout the loan term. Upon full repayment of the facility, all collateral encumbrances will be released.

Overall, the collateral structure provides sufficient asset-based security and is proportional to the size, tenor, and risk profile of the facility.


Lutrina Construction And General Supplies Limited was foundedMar 14, 2018
Start of active work/productionJan 1, 2019
Min target10,000 USDC
Investors0
Interest paymentsmonthly
Principal repaymentsbullet
Total payments10 months

Details

The financial performance of Lutrina Construction And General Supplies Limited reflects a project-based general contracting business operating under an asset-light execution model. Over the historical period, the company demonstrated consistent revenue growth and uninterrupted profitability, while margins remained structurally constrained due to reliance on subcontracted execution.

The table below summarises the Company’s historical and forecast profit and loss performance.

Metric / Year

2023

2024

2025

2026F

2027F

Total revenue

2,727,464

3,063,947

3,441,173

3,965,375

4,542,385

Gross profit

296,503

356,945

445,755

793,076

998,327

EBIT

179,457

196,926

243,741

538,053

711,220

Interest expense

0

0

0

70,833

42,500

PBT

179,457

196,926

243,741

467,220

668,720

Net profit

125,620

137,848

170,619

327,054

468,104

Revenue is generated primarily through fixed-price and hybrid general contracting agreements in the residential and small commercial segments in Nairobi. A material component of revenue and gross profit is derived from the procurement and supply of construction materials, which provides an additional margin layer within the overall contracting model.

During the historical period (2023–2025), gross margins ranged from approximately 11% to 13%, reflecting limited operating leverage under a subcontractor-led structure. EBIT margins remained below 8%, indicating modest downside protection under fixed-price execution.

The forecast period (2026–2027) assumes a structural change in the cost base driven by the introduction of owned construction equipment and limited self-performance of standardised civil works. This transition is expected to reduce subcontractor and equipment rental costs, resulting in material gross margin expansion to approximately 20%–22% and improved EBIT margins, despite higher internal operating costs and the inclusion of financing expenses.

Interest costs related to the planned loan facility are fully incorporated into the forecast results, ensuring that projected profitability is presented on a post-financing basis. Net profit growth in the forecast period is therefore driven by operational margin expansion rather than aggressive revenue assumptions.

Overall, the financial profile demonstrates consistent revenue growth, positive profitability across all periods, and a forecast improvement in margins linked to a clearly defined change in execution model rather than changes in market pricing or demand assumptions.

Margin Analysis

The table below summarises historical and projected margin development, reflecting both the asset-light operating model in the historical period and the expected impact of the planned transition to a hybrid execution model.

Metric / Year

2023

2024

2025

2026F

2027F

Gross profit margin

10.87%

11.65%


12.95%

20.00%

21.98%

EBIT margin

6.58%

6.43%

7.08%

13.57%

15.66%

PBT margin

6.58%

6.43%

7.08%

11.78%

14.72%

Net profit margin

4.61%

4.50%

4.96%

8.25%

10.31%

Margin expansion in the forecast period is driven by structural changes in execution, including reduced reliance on subcontractors and equipment rentals, while financing costs are fully reflected in net profitability.

Growth plan of Lutrina Construction And General Supplies Limited


The growth plan for Lutrina Construction And General Supplies Limited focuses on a controlled transition from a fully asset-light general contracting model to a hybrid execution model over the 2026–2027 period. The strategy is geographically concentrated in Nairobi and targets small- to mid-scale residential, commercial, and mixed-use developments that fall within the company’s established execution profile.

The primary objectives of the growth strategy are to increase control over critical-path activities, improve cost predictability under fixed-price contracts, and expand gross margins through selective self-performance of standardised civil work packages, while retaining subcontractors for specialised and non-core scopes.

Growth will be supported by an active portfolio of ongoing and advanced-stage contracts with repeat developers, providing contract-backed workload and visibility during the transition phase. The aggregate contract value of the confirmed project portfolio is approximately €2.3 million.

Planned Construction Equipment

No.

Equipment

Qty

Primary use

Unit price (€)

Total (€)

1

Excavator 20–22 t

1

Excavations, foundations, bulk earthworks

125,000

125,000

2

Backhoe loader

1

General earthworks and auxiliary works

75,000

75,000

3

Tipper truck 10–15 t

1

Soil removal, material delivery

85,000

85,000

4

Mobile concrete mixer

1

On-site concrete production

39,000

39,000

5

Steel formwork system (set)

1

Foundations, columns, slabs

55,000

55,000

6

Vibratory plates / rollers

3

Soil and base compaction

12,000

36,000

Total planned CAPEX

415,000

All equipment will be deployed across active and upcoming projects with Optiven Ltd, Fanaka Real Estate, Centum Real Estate Ltd, Fusion Group, and Username Properties Ltd. Ownership of this equipment reduces reliance on rented machinery and external civil subcontractors and improves scheduling reliability on critical-path activities.

Operational and Financial Impact

The introduction of owned equipment and limited in-house execution capacity is expected to:

  • reduce subcontractor and equipment rental costs on standardised scopes;
  • improve cost predictability and execution control under fixed-price contracts;

The growth plan does not involve expansion into new geographies or unfamiliar asset classes. All initiatives are confirmed, contract-backed, and aligned with the company’s existing technical competence and client base.

Description of the Loan

Lutrina Construction And General Supplies Limited intends to obtain a secured loan facility in the total amount of €500,000 to support the implementation of its confirmed growth plan and the transition to a hybrid execution model.

The loan is structured in two tranches and is allocated exclusively to clearly defined operational purposes directly linked to revenue-generating activities.

Loan Amount and Structure

Parameter

Description

Total loan amount

€500,000

Number of tranches

2

Interest rate

23.4% per annum (fixed)

Loan term

9 months per each tranche

Repayment structure

Monthly interest servicing; principal repaid at maturity

Total interest cost

€87,750

Total repayment amount

€587,750

Use of Loan Proceeds

Tranche

Amount (€)

Primary purpose

Tranche 1

415,000

Acquisition of construction machinery and site equipment to support partial self-perform of earthworks and concrete works.

Tranche 2

85,000

Working-capital buffer to support project execution (materials procurement, subcontractor advances, payroll, fuel and other direct costs)

The first tranche is designated for capital expenditure on standard, liquid construction equipment that will be retained for long-term operations and deployed across multiple projects. The second tranche provides limited working-capital support to smooth cash-flow timing during periods of peak execution.

The facility is not intended to refinance existing obligations or cover historical losses. All proceeds are directly linked to the execution of signed and advanced-stage contracts within the Nairobi market.

The loan structure is aligned with the company’s operating cycle, enabling execution capacity expansion while limiting cash-flow pressure during active project delivery.

Risk scoring

Total risk scoreBBB
Debt to equity1.28
LTV92%
Credit history8 / 10
Collateral typeCompany Assets

Rating BBB (the fourth tier) rests on a record of consistent revenue growth and uninterrupted profitability since 2023, a contract-backed growth plan in a market the company already serves, and collateral that covers the full loan principal.

  • D/E (Debt-to-equity) of 1.28 is moderate for a contractor that has carried no interest expense so far;
  • LTV of 92% means the €544,250 collateral package covers the €500,000 principal at 108.9%;
  • Credit history score of 8/10.

Keep in mind:

  • under fixed-price contracts Lutrina carries the execution and cost-overrun risk, and historical EBIT margins stayed below 8%;
  • the forecast margin expansion depends on a new, still untested hybrid execution model;
  • strategy, pricing and contractor selection are concentrated in the CEO and sole shareholder;
  • construction is working-capital intensive and all activity is concentrated in Nairobi.

Risk factors

Margins remained structurally constrained over the historical period due to reliance on subcontracted execution, and EBIT margins below 8% indicated modest downside protection under fixed-price execution. The company retains contractual and execution risk under its fixed-price and hybrid contracts, so results depend on disciplined project selection, accurate cost estimation and effective subcontractor coordination.

Competitive pressure and working-capital intensity remain structural features of the sector. Future performance is therefore more closely linked to execution discipline, cost management and cash-flow control than to macro-level demand conditions.

The mitigants are built into the plan: the growth plan does not involve expansion into new geographies or unfamiliar asset classes, and all initiatives are confirmed, contract-backed and aligned with the company’s existing technical competence and client base. The facility is not intended to refinance existing obligations or cover historical losses; all proceeds are directly linked to the execution of signed and advanced-stage contracts within the Nairobi market.

Financials

Revenue 2025€3.44M
Net profit 2025€171k
Gross margin 202512.95%
Confirmed portfolio€2.3M
€ millions
€2.73M2.73
+12%€3.06M3.06
+12%€3.44M3.44
+15%€3.97M*3.97*
+14%€4.54M*4.54*
2023202420252026F2027F

* 2026–2027 are management forecasts; net profit is shown after interest on the planned loan facility
Commercial Construction

Lutrina has grown revenue every year while staying profitable. The forecast assumes that owned equipment lifts margins, not that revenue jumps: interest on the planned facility is already deducted from the forecast profit.

Steady growth

  • Revenue rose from €2.73M in 2023 to €3.06M in 2024 and €3.44M in 2025.
  • It is forecast to reach €3.97M in 2026 and €4.54M in 2027.
  • A confirmed portfolio of about €2.3M of contracts with repeat developers backs the transition.

Profitable every year

  • Net profit grew from €126k in 2023 to €138k in 2024 and €171k in 2025.
  • The forecast is €327k in 2026 and €468k in 2027, after interest.

Margin expansion from own equipment

  • Gross margin was 10.87%–12.95% in 2023–2025 under a fully subcontracted model.
  • With owned machinery replacing rentals and civil subcontractors, it is forecast at 20.00% in 2026 and 21.98% in 2027.
  • Net margin is forecast to rise from 4.96% in 2025 to 10.31% in 2027.

Market

Core East African construction markets are worth about €55 billion (2024), and Kenya’s market is estimated at €6.0–6.3 billion a year, driven by urbanisation and a persistent housing undersupply in Nairobi and its commuter belt. Lutrina’s segment — small- and mid-scale residential and commercial projects — is fragmented and repeatable, with contractors competing on execution discipline and cost control. Competitive pressure and working-capital intensity remain structural features of the sector.

Financial performance

The financial performance of Lutrina reflects a project-based general contracting business operating under an asset-light execution model. Over the historical period, the company demonstrated consistent revenue growth and uninterrupted profitability, while margins remained structurally constrained due to reliance on subcontracted execution.

Profit and loss, EUR (2023–2027F)

Metric2023202420252026F2027F
Total revenue2,727,4643,063,9473,441,1733,965,3754,542,385
Gross profit296,503356,945445,755793,076998,327
EBIT179,457196,926243,741538,053711,220
Interest expense00070,83342,500
PBT179,457196,926243,741467,220668,720
Net profit125,620137,848170,619327,054468,104

Revenue is generated primarily through fixed-price and hybrid general contracting agreements in the residential and small commercial segments in Nairobi. A material component of revenue and gross profit is derived from the procurement and supply of construction materials, which provides an additional margin layer within the overall contracting model.

During the historical period (2023–2025), gross margins ranged from approximately 11% to 13%, reflecting limited operating leverage under a subcontractor-led structure. The forecast period (2026–2027) assumes a structural change in the cost base driven by the introduction of owned construction equipment and limited self-performance of standardised civil works. This transition is expected to reduce subcontractor and equipment rental costs, resulting in material gross margin expansion to approximately 20%–22% and improved EBIT margins, despite higher internal operating costs and the inclusion of financing expenses.

Interest costs related to the planned loan facility are fully incorporated into the forecast results, ensuring that projected profitability is presented on a post-financing basis. Net profit growth in the forecast period is therefore driven by operational margin expansion rather than aggressive revenue assumptions. Overall, the financial profile shows positive profitability across all periods and a forecast improvement in margins linked to a clearly defined change in execution model rather than changes in market pricing or demand assumptions.

Margin analysis

The table below summarises historical and projected margin development, reflecting both the asset-light operating model in the historical period and the expected impact of the planned transition to a hybrid execution model.

Metric2023202420252026F2027F
Gross profit margin10.87%11.65%12.95%20.00%21.98%
EBIT margin6.58%6.43%7.08%13.57%15.66%
PBT margin6.58%6.43%7.08%11.78%14.72%
Net profit margin4.61%4.50%4.96%8.25%10.31%

Margin expansion in the forecast period is driven by structural changes in execution, including reduced reliance on subcontractors and equipment rentals, while financing costs are fully reflected in net profitability.

Growth plan

The growth plan focuses on a controlled transition from a fully asset-light general contracting model to a hybrid execution model over the 2026–2027 period. The strategy is geographically concentrated in Nairobi and targets small- to mid-scale residential, commercial and mixed-use developments that fall within the company’s established execution profile.

The primary objectives are to increase control over critical-path activities, improve cost predictability under fixed-price contracts, and expand gross margins through selective self-performance of standardised civil work packages, while retaining subcontractors for specialised and non-core scopes. Growth will be supported by an active portfolio of ongoing and advanced-stage contracts with repeat developers, providing contract-backed workload and visibility during the transition phase. The aggregate contract value of the confirmed project portfolio is approximately €2.3 million.

Planned construction equipment

No.EquipmentQtyPrimary useUnit price (€)Total (€)
1Excavator 20–22 t1Excavations, foundations, bulk earthworks125,000125,000
2Backhoe loader1General earthworks and auxiliary works75,00075,000
3Tipper truck 10–15 t1Soil removal, material delivery85,00085,000
4Mobile concrete mixer1On-site concrete production39,00039,000
5Steel formwork system (set)1Foundations, columns, slabs55,00055,000
6Vibratory plates / rollers3Soil and base compaction12,00036,000
Total planned CAPEX415,000

All equipment will be deployed across active and upcoming projects with Optiven Ltd, Fanaka Real Estate, Centum Real Estate Ltd, Fusion Group and Username Properties Ltd. Ownership of this equipment reduces reliance on rented machinery and external civil subcontractors and improves scheduling reliability on critical-path activities.

Operational and financial impact

The introduction of owned equipment and limited in-house execution capacity is expected to:

  • reduce subcontractor and equipment rental costs on standardised scopes;
  • improve cost predictability and execution control under fixed-price contracts.

Market assessment

Lutrina operates within the East African construction market, with its activities concentrated in Kenya and primarily in the Nairobi metropolitan area. The regional construction sector is supported by long-term structural drivers, including rapid urbanisation, population growth and sustained demand for residential and commercial real estate.

At a regional level, the combined construction industry value of core East African markets is estimated at approximately €55 billion (2024), reflecting a multi-year growth trajectory driven by both public infrastructure investment and private-sector development. Within this context, Kenya represents one of the most developed and liquid construction markets in the region.

Kenya’s construction market is estimated at approximately €6.0–6.3 billion annually, with projected growth supported by persistent housing undersupply, urban concentration in Nairobi and its commuter belt, and continued public infrastructure spending that indirectly stimulates private real estate development. Demand is particularly strong in small- to mid-scale residential estates, mid-rise apartment buildings and mixed-use projects targeted at affordable and mid-income segments.

Lutrina’s addressable market is the segment of small- and mid-scale residential and commercial projects where general contractors compete primarily on execution discipline, cost control, subcontractor coordination and procurement capability rather than on proprietary construction technologies or balance-sheet scale. This segment is characterised by a high volume of repeatable projects and developer-led demand.

The Kenyan general contracting market is fragmented, with numerous small and mid-sized contractors competing alongside larger firms focused on infrastructure and high-value commercial developments. In this environment, differentiation is achieved through reliability of execution, control of subcontractor performance, and the ability to manage material sourcing and scheduling under fixed-price or hybrid contract structures.

Overall, the market environment offers sustained demand for Lutrina’s core services.

Collateral breakdown

Construction machinery and equipment (loan-financed) · €352.8K€150K
Construction machinery and equipment (loan-financed)€352,750
Corporate reserves€150,000
Toyota Land Cruiser Prado J150 (2022)€41,500
Total pledged€544,250Equipment at nominal cost less a 15% discount; other assets at estimated value

The €500,000 facility is backed by three kinds of assets worth €544,250 in total — 108.9% of the loan principal.

1. Equipment bought with the loan — €352,750

Tranche 1 buys €415,000 of construction machinery: an excavator, a backhoe loader, a tipper truck, a concrete mixer, a formwork set and compaction equipment.

  • The equipment is pledged to the lender.
  • It is valued at a 15% discount to purchase cost to reflect liquidation assumptions.
  • It is standard machinery with an established secondary market.

2. Additional collateral — €191,500

  • Corporate reserves of €150,000;
  • a Toyota Land Cruiser Prado J150 (2022), estimated at €41,500.

The package fully covers the principal, although with a thinner buffer than the total repayment of €587,750. All collateral encumbrances are released once the facility is repaid in full.

Loan collateral

The €500,000 loan facility is secured by a combination of loan-financed construction equipment, corporate assets and personal collateral provided by the owner of Lutrina. The collateral structure is asset-based, transparent and directly linked to the company’s operating activities.

Loan-financed equipment (pledged to the lender)

For collateral valuation purposes, the construction equipment acquired under Tranche 1 is valued on a conservative basis, applying a 15% discount to nominal purchase cost to reflect liquidation assumptions.

Asset categoryNominal value (€)DiscountCollateral value (€)
Construction machinery and equipment415,00015%352,750

Additional collateral

AssetEstimated value (€)
Toyota Land Cruiser Prado J150 (2022)41,500
Corporate reserves150,000
Total additional collateral191,500

Collateral coverage

MetricValue (€)
Total collateral value544,250
Loan principal500,000
Collateral coverage ratio108.9%

The pledged assets consist of standard, marketable construction equipment with established secondary-market liquidity, supplemented by liquid corporate reserves and personal collateral. The collateral package fully covers the loan principal and provides an adequate recovery buffer for the lender.

The pledged equipment is integral to the execution of the company’s active and confirmed project portfolio and is expected to remain in continuous operational use throughout the loan term. Upon full repayment of the facility, all collateral encumbrances will be released. Overall, the collateral structure provides sufficient asset-based security and is proportional to the size, tenor and risk profile of the facility.

Description of the loan

Lutrina intends to obtain a secured loan facility in the total amount of €500,000 to support the implementation of its confirmed growth plan and the transition to a hybrid execution model. The loan is structured in two tranches and is allocated exclusively to clearly defined operational purposes directly linked to revenue-generating activities.

Loan amount and structure

ParameterDescription
Total loan amount€500,000
Number of tranches2
Interest rate23.4% per annum (fixed)
Loan term9 months per each tranche
Repayment structureMonthly interest servicing; principal repaid at maturity
Total interest cost€87,750
Total repayment amount€587,750

Use of loan proceeds

TrancheAmount (€)Primary purpose
Tranche 1415,000Acquisition of construction machinery and site equipment to support partial self-performance of earthworks and concrete works
Tranche 285,000Working-capital buffer to support project execution (materials procurement, subcontractor advances, payroll, fuel and other direct costs)
Total500,000

The first tranche is designated for capital expenditure on standard, liquid construction equipment that will be retained for long-term operations and deployed across multiple projects. The second tranche provides limited working-capital support to smooth cash-flow timing during periods of peak execution.

The loan structure is aligned with the company’s operating cycle, enabling execution capacity expansion while limiting cash-flow pressure during active project delivery.

How the loan pays out

Your 012345678901234567890,012345678901234567890012345678901234567890012345678901234567890 USDC investment behaves like a 10-month bond: monthly interest payments, then principal back at month 012345678901234567890.

DateInterestPrincipalTotal
Net profit+012345678901234567890.012345678901234567890012345678901234567890 USDC
Total return012345678901234567890.012345678901234567890012345678901234567890 USDC

Borrower

Lutrina Construction And General Supplies LimitedWangige, Kenya · founded 2018
Lutrina Construction And General Supplies Limited

Lutrina Construction And General Supplies Limited is a privately owned Kenyan construction company incorporated on 14 March 2018. The company operates primarily in Nairobi and its surrounding metropolitan areas, focusing on small- to mid-scale residential and commercial construction projects.

The company functions as an asset-light general contractor, assuming full responsibility for project coordination, subcontractor management, procurement of construction materials, cost control, quality supervision, and client communication. Physical construction works are executed through a network of specialised subcontractors, while Lutrina retains contractual and execution risk under fixed-price or hybrid (fixed price with approved variations) contracts.

Reg No: PVT-Q7UZ6R6lutrina-construction.com

About the company

Lutrina Construction And General Supplies Limited is a privately owned Kenyan construction company incorporated on 14 March 2018. The company operates primarily in Nairobi and its surrounding metropolitan areas, focusing on small- to mid-scale residential and commercial construction projects.

The company functions as an asset-light general contractor, assuming full responsibility for project coordination, subcontractor management, procurement of construction materials, cost control, quality supervision and client communication. Physical construction works are executed through a network of specialised subcontractors, while Lutrina retains contractual and execution risk under fixed-price or hybrid (fixed price with approved variations) contracts.

In addition to general contracting services, Lutrina independently procures and supplies construction materials to its project sites. Material sourcing and delivery represent a distinct margin component alongside the general contracting fee, contributing to overall project profitability.

Corporate identifiers: registration number PVT-Q7UZ6R6; registered address Shamata Building, Nakuru–Nairobi Highway, Kinoo, Kabete District, Kiambu County (Wangige), Kenya; active work since 2019.

Leadership and operating model

The company is led by its CEO and sole shareholder, Doreen Kendi Mukami, an engineer by training with prior professional experience in large contracting and real estate development organisations in Kenya. Strategic decision-making, pricing discipline, contractor selection and execution oversight are centralised at management level, reflecting a management-driven operating model rather than asset- or technology-led execution.

Lutrina does not maintain permanent in-house construction crews or heavy equipment. As part of its confirmed development strategy, the company plans to selectively introduce owned construction equipment and transition toward a hybrid execution model, enabling limited self-performance of standardised civil work packages while retaining a subcontractor-led structure.

The company’s target clients include private property developers, landowners and small commercial investors seeking predictable delivery under a single coordinating contractor. The operating model emphasises flexibility, controlled scaling and low fixed costs, while relying on disciplined project selection, accurate cost estimation and effective subcontractor coordination.

Track record and clients

Lutrina has established a track record of delivering comparable residential and commercial projects for SME and institutional developers in Nairobi, supporting its positioning within a repeatable market segment. Repeat engagements and a portfolio of completed projects indicate operational relevance rather than reliance on one-off or atypical contracts.

Active and upcoming projects are with Optiven Ltd, Fanaka Real Estate, Centum Real Estate Ltd, Fusion Group and Username Properties Ltd.

Annual interest
23.40 %
Term
10 months
Net profit
Voucher
+0 USDC
Total return0.00012345678901234567890.012345678901234567890012345678901234567890 USDC
Sign up to Invest