Grain Processing
KIMRINES SUPPLIERS LIMITED buys pulses from farmers in Eastern Kenya, processes them at its own cleaning and calibration facility, and supplies exporters, packers and wholesalers. Revenue reached EUR 1.21 million in January–October 2026, already exceeding the full-year 2025 result. The company is requesting EUR 500,000 to finance deliveries under two signed framework agreements with Kenyan buyers.
회사 배경
KIMRINES SUPPLIERS LIMITED는 케냐 키투이 카운티 무토모에 기반을 둔 농업 거래 및 가공 기업입니다. 2022년 1월 26일에 설립되어 2023년부터 거래를 시작했습니다.
이 회사는 윌버포스 카유기라 루바이(Wilberforce Kayugira Luvai)가 소유 및 경영하며, 그가 지분 100%를 보유하고 이사직을 맡고 있습니다. 그는 회사의 조달, 공급업체 관계, 가격 책정, 재고 계획 및 품질 관리를 관리합니다.
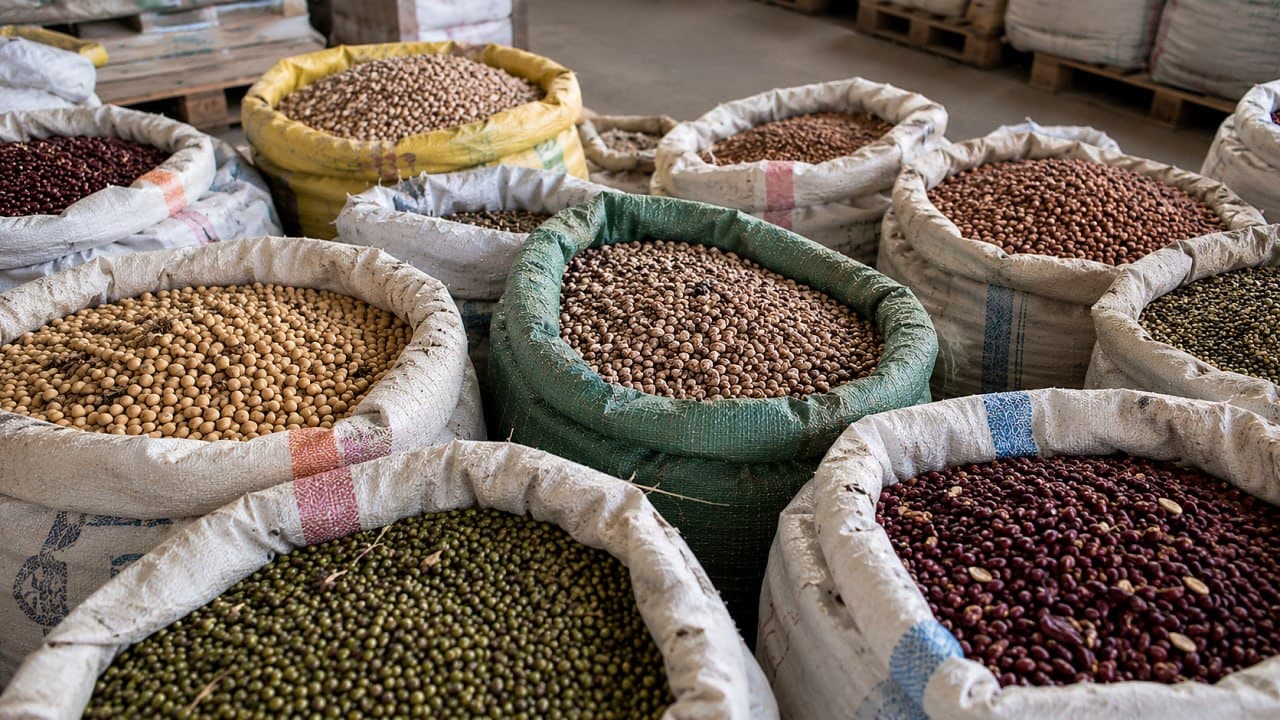
KIMRINES는 주로 키투이 및 케냐 동부의 농민 그룹, 협동조합, 지역 집하업체로부터 녹두(그린 그램), 동부콩, 비둘기콩을 구매합니다. 생산물을 세척, 등급 분류 및 교정한 후 케냐와 탄자니아의 수출업체, 포장업체, 도매업체 및 식품 제조업체에 판매합니다.
2026년, 당사는 자체 세척 및 교정 라인을 가동하여 외부 가공업체에 대한 의존도를 줄였습니다.
사업 내용
KIMRINES는 콩류 공급망의 여러 단계를 처리합니다:
농부, 협동조합 및 지역 집하업체로부터 콩 구매.
구매자 사양에 맞게 곡물 세척 및 교정.
생산물을 25kg, 50kg, 90kg 자루로 등급 분류 및 포장.
수확기 사이에 판매할 준비된 재고 보관.
수출업체, 포장업체, 도매업체 및 식품 제조업체에 공급.
탄자니아 무역 회사로의 수출 물량 배송.
당사는 주로 키투이 카운티와 케냐 동부의 다른 지역에서 생산물을 조달합니다. 처리 라인의 용량은 원곡 기준 시간당 약 2~4톤입니다.
운영 방식
KIMRINES는 일관된 물량과 품질이 필요한 상업적 구매자와 소농 사이에서 중개 역할을 합니다.
당사는 수확기에 콩을 구매하여 표준 등급으로 가공한 뒤 연중 판매합니다. 이를 통해 구매자는 여러 농부로부터 소량의 물량을 직접 조달하고 세척하는 수고를 덜 수 있습니다.
회사의 세 가지 주요 판매 채널은 다음과 같습니다:
국내 구매자: 케냐 내 수출업체, 포장업체, 도매업체 및 식품 제조업체에 공급.
프레임워크 계약: 구매자는 합의된 공급 조건에 따라 매월 발주합니다. KIMRINES는 예정된 배송을 위해 필요한 재고를 구매하고 준비합니다.
수출 물량: 당사는 등급이 분류된 녹두를 탄자니아 무역 회사에 공급하며, 트럭 단위로 배송됩니다.
또한, 당사는 계약 납품에 할당되지 않은 잉여 재고도 판매합니다.
KIMRINES는 농산물에 대한 우선 접근권을 받는 대가로 선별된 농민 그룹에 타포린과 밀폐형 보관 가방을 제공하여 지원합니다. 이는 수확기 동안의 공급을 확보하는 데 도움이 됩니다.
팀 및 채용 계획
회사는 창립자이자 유일한 주주인 윌버포스 카유기라 루바이가 관리합니다. 그는 조달, 공급업체 관계, 가격 책정, 재고 관리 및 품질 관리를 감독합니다.
가공 인력은 처리되는 곡물의 양에 따라 비정기적으로 고용됩니다. 운송 및 회계는 아웃소싱되며, 전문적인 상업 및 조달 지원은 프로젝트 단위로 제공됩니다.
출처에는 현재 직원 수나 별도의 채용 계획이 명시되어 있지 않습니다. 당사는 기존 운영 구조를 활용하여 증가하는 물량을 처리할 것으로 예상합니다.
제품 및 수익원
KIMRINES는 세 가지 주요 제품 라인을 보유하고 있습니다.
녹두 — 핵심 사업
녹두는 조달 및 판매량 측면에서 당사의 주요 제품입니다. 탄자니아 고객을 포함한 국내 구매자와 수출업체에 공급됩니다.
동부콩
당사는 주로 국내 구매자를 위해 붉은 동부콩을 포함한 동부콩을 매매합니다.
비둘기콩
통비둘기콩은 국내 및 수출 시장 모두에 공급됩니다.
수익은 가공, 포장, 보관 및 배송 비용을 제외한 후, 원두 구매 가격과 세척 및 등급 분류된 생산물 판매 가격의 차액에서 발생합니다.
녹두와 동부콩은 연 2회 수확기(1~2월, 6~8월)에 구매합니다. 비둘기콩은 주로 7월부터 10월 사이에 수확됩니다.
성장 계획
당사는 프레임워크 계약에 따른 공급 물량을 늘리고 소싱 및 수출 활동을 확장하여 성장할 계획입니다.
주요 우선순위는 다음과 같습니다:
체결된 두 건의 프레임워크 계약 이행: 2026년 11월부터 2027년 7월까지 두 명의 케냐 구매자에게 1,378톤의 가공된 콩 공급.
계절별 조달 증가: 수확기에 더 많은 물량을 구매하고 정기 배송을 위한 재고 보유.
농민 관계 확장: 추가적인 농민 그룹 및 인근 카운티로부터 소싱.
수출 시장 개발: 향후 2~3년 내에 우간다, 콩고민주공화국, 남수단, 인도 및 태국을 타겟으로 함.
제품 및 포장 옵션 확장: 구매자 요구사항을 충족하기 위해 추가적인 콩 등급 및 포장 형태 제공.
자체 가공 라인은 더 큰 물량을 처리하고 외부 세척 및 교정 비용을 절감하는 데 도움이 될 것입니다.
대출 요청
항목 | 세부사항 |
총 대출액 | 500,000 유로 |
인출 구조 | 일시 인출 |
1단계 | 288,247 유로 |
2단계 | 211,753 유로 |
이자율 | 연 21.3% (고정) |
대출 기간 | 11개월 |
이자 지급 | 월별 |
월 이자 | 8,875 유로 |
기간 총 이자 | 97,625 유로 |
원금 상환 | 만기 일시 상환 |
총 상환액 | 597,625 유로 |
자금 사용처 | 두 건의 체결된 프레임워크 계약을 위한 운영 자금 |
1단계는 576,649 유로 상당의 콩 수출업체와의 계약에 자금을 지원합니다. 2단계는 401,227 유로 상당의 콩 및 곡물 포장업체와의 계약에 자금을 지원합니다.
총 계약 가치는 977,876 유로입니다. 본 대출은 콩 구매 및 관련 운영 자금으로 사용됩니다. 장비 구입이나 일반 회사 경비로는 사용되지 않습니다.
운영 자금 필요액의 정점은 2027년 2월 556,365 유로입니다. 당사는 나머지 56,365 유로를 자체 자원 및 고객 수입으로 충당할 예정입니다.
리스크 평가
The BBB rating reflects the company's growing revenue, positive operating results, established farmer relationships and investment in its own processing line. The company has also secured two signed framework agreements to support the proposed financing.
However, both framework buyers are new customers, and the company must manage substantial seasonal purchases before receiving payment for deliveries.
Keep in mind:
The company depends heavily on its founder for procurement, pricing and commercial decisions.
The two framework buyers are new customers, so payment performance has not yet been established.
The agreements require 1,378 tonnes of finished product over nine months.
Buyers have payment terms of up to 60 days after delivery.
Peak working capital requirements of EUR 556,365 exceed the loan amount.
Pulse supply depends on harvest conditions, rainfall and seasonal availability.
Commodity price movements and export restrictions could affect sales and margins.
The company earns revenue mainly in Kenyan shillings but must repay the loan in euros.
재무
* 2026–2027 are the company's forecast.
Financial Performance
KIMRINES has grown its revenue steadily since starting commercial operations in 2023. Revenue increased from EUR 665,689 in 2023 to EUR 1,184,780 in 2025.
In January–October 2026, revenue reached EUR 1,210,751, already exceeding the full-year 2025 result. Net profit also increased to EUR 69,748, compared with EUR 56,184 for the whole of 2025.
The company's gross margin improved from 9.8% in 2025 to 12.5% in January–October 2026. This improvement was supported by the commissioning of its own cleaning and calibration line.
Historical performance
Actual performance (EUR) | 2023 | 2024 | 2025 | Jan–Oct 2026 |
Revenue | 665,689 | 961,549 | 1,184,780 | 1,210,751 |
Cost of goods sold | 611,162 | 871,769 | 1,068,716 | 1,059,014 |
Gross profit | 54,527 | 89,780 | 116,064 | 151,737 |
Operating expenses | 16,815 | 25,185 | 32,340 | 43,285 |
EBITDA | 37,712 | 64,595 | 83,724 | 108,452 |
Net profit | 26,065 | 42,892 | 56,184 | 69,748 |
The company has been profitable in every reporting period since it started trading. Its January–October 2026 net profit was already higher than its full-year 2025 result.
Forecast (EUR) | 2026 | 2027 |
Revenue | 1,681,615 | 2,369,581 |
Cost of goods sold | 1,455,457 | 1,991,475 |
Gross profit | 226,158 | 378,106 |
Operating expenses | 56,514 | 79,380 |
EBITDA | 169,644 | 298,726 |
Net profit | 98,630 | 144,033 |
EBITDA margin | 10.1% | 12.6% |
The forecast expects revenue to grow by 40.9% in 2027. The two financed agreements are expected to contribute EUR 760,570, or 32.1% of forecast 2027 revenue.
Track record in 2026
Revenue from January to October: EUR 1,210,751.
EBITDA: EUR 108,452.
Net profit: EUR 69,748.
Gross margin: 12.5%.
EBITDA margin: 9.0%.
No interest expense recorded in the historical periods.
Commercial Pipeline
KIMRINES has five documented customer engagements with a combined stated value of EUR 1,199,464.
Buyer | Products | Commercial status | Value (EUR) |
Kenyan pulse exporter | Pulses | Signed, nine-month agreement | 576,649 |
Kenyan pulse and cereals packer | Pulses and cereals | Signed, nine-month agreement | 401,227 |
Kenyan food company | Pulses | Existing, self-funded engagement | 101,605 |
Tanzanian pulse exporter | Pulses | Existing, self-funded engagement | 79,989 |
Tanzanian pulse exporter | Pulses | Existing, self-funded engagement | 39,994 |
Total | 1,199,464 |
The two signed agreements account for EUR 977,876 and cover 1,378 tonnes of finished product. Deliveries are scheduled monthly from November 2026 to July 2027.
The three self-funded engagements have a combined indicative annual value of EUR 221,588. These activities continue separately from the proposed loan.
The total pipeline combines nine-month contract values with indicative annual sales, so the figures do not cover the same period.
Pulses
Pulses are an important food and agricultural trading category in Kenya and international markets. The global pulses market was valued at approximately EUR 91.9 billion in 2025 and is forecast to reach EUR 122.8 billion by 2034.
Kenya is a significant producer of mung beans, pigeon peas and cowpeas. In 2025, production reached approximately:
106,000 tonnes of mung beans.
88,000 tonnes of pigeon peas.
87,500 tonnes of cowpeas.
Around 90% of Kenya's green gram production comes from the Eastern region. Kitui County is an important production area, giving KIMRINES access to local farmer supply.
Export markets
Kenyan pulses are traded in regional and international markets. Tanzania is an important regional trading destination, while India, Pakistan, the UAE and China are among the wider markets for pulses.
KIMRINES began supplying export lots to Tanzania in February 2026. It plans to expand into additional African and Asian markets over the next two to three years.
Competition
KIMRINES competes with international agricultural traders such as ETG, AGT Food and Ingredients and Olam Agri, as well as local aggregators, cooperatives and informal brokers.
Its advantage is its combination of direct sourcing relationships, in-house cleaning and calibration, and the ability to hold standard grades for delivery between harvest periods.
The main market risks include seasonal supply, weather conditions, commodity price changes, storage quality and export restrictions.
담보 구성
Collateral | Base value (EUR) | Liquidation value (EUR) |
Existing operational assets | 68,448 | 50,367 |
Contract goods and receivables | 352,410 | 299,549 |
Cash in pledged account | 155,913 | 155,913 |
Total collateral | 576,771 | 505,829 |
Valuation and Coverage
Coverage metric | Value |
Loan principal | EUR 500,000 |
Total repayment | EUR 597,625 |
Total collateral — base value | EUR 576,771 |
Total collateral — liquidation value | EUR 505,829 |
Base collateral coverage of principal | 115.4% |
Liquidation collateral coverage of principal | 101.2% |
LTV at base value | 0.87 |
LTV at liquidation value | 0.99 |
The liquidation value covers 101.2% of the loan principal. This includes EUR 155,913 in pledged cash, valued at 100%.
Collateral coverage is expected to improve as the financed stock is purchased and delivered. Liquidation coverage of principal is forecast at 102.4% in December 2026, 110.4% at the February 2027 procurement peak and 129.3% in August 2027.
- Existing operational assets — EUR 68,448 base value
This includes the company's existing processing and handling equipment. The liquidation value is EUR 50,367. Installation, wiring and commissioning costs are excluded because they do not have separate resale value.
- Contract goods and receivables — EUR 352,410 base value
This covers stock purchased for the framework agreements and receivables arising from financed deliveries.
The stock is kept separate, tagged and reported monthly, and is available for inspection. Once goods are delivered, the security transfers from stock to the buyer's receivable.
- Cash in pledged account — EUR 155,913
The pledged cash is valued at 100%. The lender controls the account until the funds are used for approved purchases.
As the company uses the cash to buy stock, the collateral shifts to goods and receivables. Buyer payments then return to the pledged account.
Additional security
The company also provides:
Assignment of current and future claims under both framework agreements, with a combined contract value of EUR 977,876.
A personal guarantee from the owner.
The main source of repayment is expected to be collections from the two framework agreements. The collateral provides additional protection if the business performs below expectations.
대출 상환 방식
USDC 투자는 11개월 채권처럼 작동합니다: 매월 이자가 지급되고 개월 차에 원금이 돌아옵니다.
| 일자 | 이자 수익 | 원금 | 총합 |
|---|
차입자 정보
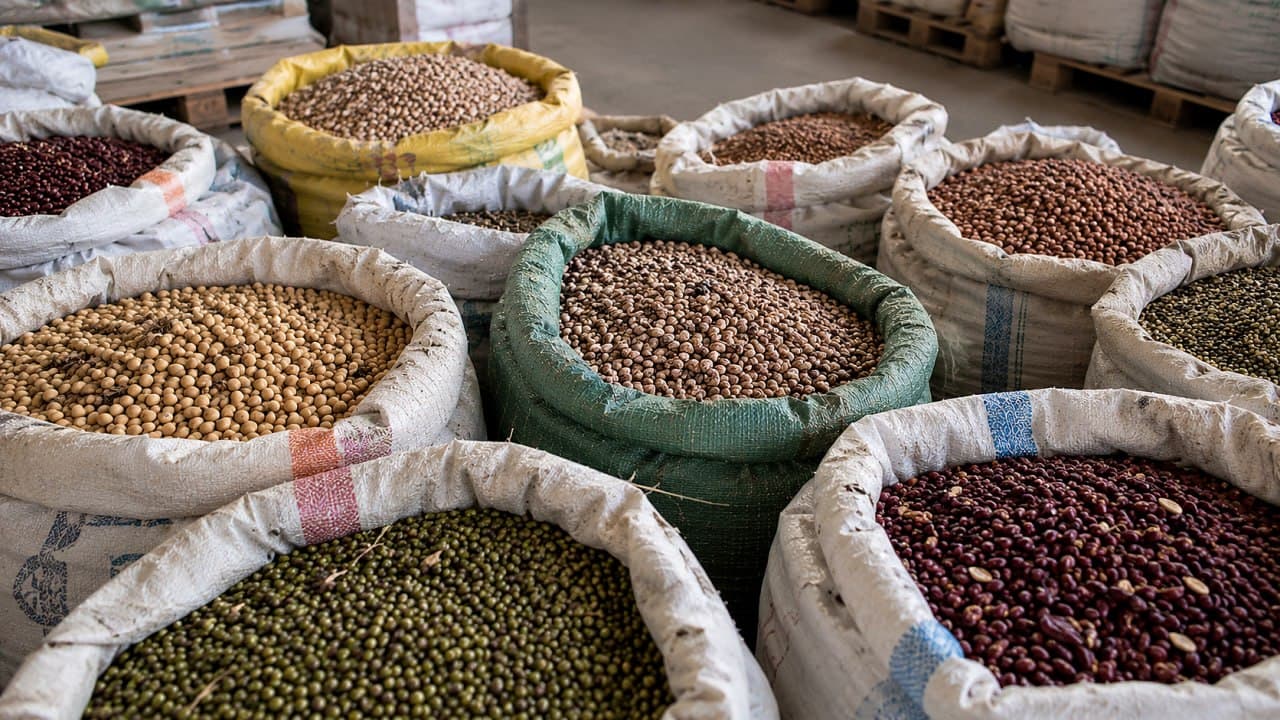
KIMRINES SUPPLIERS LIMITED는 케냐의 농산물 무역 및 가공 회사입니다. 농부와 현지 수집가로부터 녹두, 동부콩, 비둘기콩을 구매하여 세척 및 등급 분류를 거친 후 수출업체, 포장업체, 도매업체 및 식품 제조업체에 공급합니다.
이 회사는 지분 100%를 보유한 Wilberforce Kayugira Luvai가 소유 및 경영하고 있습니다. 2026년에 자체 세척 및 보정 라인을 가동했으며, 2026년 2월부터 탄자니아로 수출 물량을 공급하기 시작했습니다.
KIMRINES의 2025년 매출은 1,184,780유로였으며, 2026년 첫 10개월 동안은 1,210,751유로의 매출을 기록했습니다. 동사는 케냐 구매자들과 체결한 두 건의 기본 계약에 따른 구매 및 배송 자금을 조달하기 위해 500,000유로의 대출을 사용할 계획입니다.