Log InSign Up
  • Primary
  • Secondary
  • Cryptolending
  • Token
  • My investments
  • More
    Leagues
    Transactions
    Referral program
    Help & Feedback
    Twitter
    Telegram
    LinkedIn
  • Primary
  • Secondary
  • Cryptolending
  • Token
  • My investments
  • More
Log InSign Up
PrimarySecondaryCryptolendingInvestments
PrimarySecondaryCryptolendingTokenMy investments
LeaguesTransactionsReferral programHelp & Feedback
TwitterTelegramLinkedIn
Trustpilot
  • Terms and Conditions
  • Privacy Policy
  • Help & Feedback
  • WEB2 Platform
📍 LogisticsID: 459

Korean Parts

18,481.10USDC
92.41% of 20,000 USDC
Fundedon Jun 23, 2026
Funded date
Jun 23, 2026
Loan period
9 months
Annual interest
22.10 %

Fundraising is closed. Positions in this deal can be bought from other investors on the Secondary market.

Repayment
Overview
Risk scoring
Financials
Collateral
Borrower
Working capital for twenty EVs bound for Georgia

Capacity is raising €550k in two tranches to buy ten Genesis G80 Electrified and ten Hyundai Ioniq 5 in Korea and ship them from Busan to Batumi under two contracts worth €800,400 combined.

18,481.10USDC
92.41% of 20,000 USDC
Risk score: BBB9 months22.10 %Funded
Korean Parts

Capacity Co., Ltd. is a South Korea–based B2B export trading company specialising in the wholesale export of Korean automotive spare parts (genuine, OEM and aftermarket components for Hyundai, Kia and Genesis vehicles) and used Korean-manufactured automobiles. The company operates as a trading principal and export consolidator: it sources products from Korean manufacturers and authorised distributors, aggregates orders for overseas buyers, performs quality control and packaging, and coordinates export logistics through the ports of Pyeongtaek and Busan. The company is based in Pyeongtaek, Gyeonggi Province — in direct proximity to tier-one Korean parts suppliers and major export terminals.

The spare parts export line is the core activity, accounting for approximately 75–80% of total revenue, while used vehicle exports contribute roughly 20–25%. Both lines serve the same B2B client base and utilise the same logistics infrastructure. The spare parts portfolio covers three sourcing tiers: genuine parts (via Hyundai Mobis and official channels), OEM components and aftermarket alternatives, with gross margins ranging between 20% and 28%. Used vehicles are sourced through Korean wholesale auctions and leasing companies, with margins of 15–21%. The blended gross margin across both lines is approximately 22–24%.

The operating model is order-driven and asset-light: procurement is performed against confirmed customer orders, which limits inventory risk. The operating cycle begins with a customer advance payment (typically 30–50% of order value), followed by procurement, inspection, packaging and export shipment. Suppliers are paid in full at procurement, while customers settle the remaining balance after receipt of shipping documentation, creating a working capital gap of 20–60 days per transaction. Scalability is linked primarily to working capital availability rather than to fixed infrastructure.

The company was established in late 2023 and funded entirely from the owner’s personal resources: registered capital of EUR 1,333 plus a personal contribution of EUR 78,000 invested during 2023–2024, with no external debt at the start-up stage. In 2024, the first full year of operations, revenue reached EUR 684k. In 2025, revenue grew to EUR 1.2m and net profit rose to EUR 84k. Capacity currently exports to five principal markets — Kazakhstan, the UAE, Libya, Turkey and Kyrgyzstan — with secondary activity in Uzbekistan and Georgia. Client relationships are exclusively B2B, developed through trial orders followed by increasing volumes; the company does not operate under long-term supply agreements. The client base remains relatively concentrated at this stage, with several anchor buyers accounting for a significant share of revenue.

The internal team consists of four employees covering procurement coordination, logistics and warehouse operations. Accounting, tax reporting and customs brokerage are outsourced. The existing warehouse and logistics setup (approximately 640 sq.m) supports 7–10 export shipments per month and does not constrain moderate growth.

Key figure and expertise

Capacity is solely owned and managed by Ten Andrey Vladimirovich (born 1978), who serves as director and sole shareholder. Prior to founding the company, Mr. Ten accumulated over 15 years of experience in the automotive industry: first as co-owner and operational manager of an automotive service centre, then in a senior management position at an automotive dealership responsible for commercial operations, inventory management and supplier coordination. This progression provided hands-on knowledge of vehicle sourcing, parts procurement, B2B pricing and logistics.

Within Capacity, the CEO is directly responsible for all strategic decisions, key client negotiations, vehicle procurement at Korean wholesale auctions and financial oversight. The procurement and client manager handles day-to-day order execution independently, and operational processes are documented, but strategic and commercial functions remain concentrated in a single individual. This creates a structural key-person dependency recognised as characteristic of the company’s current development stage.

Loan Collateral

The EUR 550,000 facility is secured by a two-layer collateral structure combining existing company-owned operational assets and the 20 electric vehicles acquired under the Georgia contracts using loan proceeds. Collateral is valued at both nominal and conservative liquidation values, with liquidation discounts of 20% for existing operational assets and 10% for contract vehicles.

Collateral composition and coverage

Collateral source

Nominal value (EUR)

Liquidation value (EUR)

Existing operational assets (80%)

61,290

49,032

Contract vehicles / assigned rights (90%)

590,000

531,000

Total collateral

651,290

580,032


Coverage metric

Value

Loan principal

EUR 550,000

Total collateral (nominal)

EUR 651,290

Total collateral (liquidation)

EUR 580,032

Nominal coverage ratio

1.18×

Liquidation coverage ratio

1.05×


  • Existing operational assets include warehouse infrastructure, materials handling equipment, two vehicles (Hyundai Porter II and Hyundai Tucson, both 2021), CCTV, IT equipment and office furniture. Aggregate book value.
  • Contract vehicles (20 units — ten Genesis G80 Electrified and ten Hyundai Ioniq 5) form the principal collateral layer. During procurement and transit, vehicles are directly pledged in favour of the lender. After delivery in Batumi, vehicles are transferred to the buyer on instalment terms with a registered lien in favour of Capacity, recorded in the National Agency of Public Registry of Georgia. The lender’s security transitions from a direct pledge on physical assets to a claim on Capacity’s enforceable contractual rights and security interests, including the registered liens and the right to receive outstanding instalment payments.
  • The 90% liquidation rate on contract vehicles reflects the high liquidity and active secondary market for Korean electric vehicles in the 2022–2024 model year range.


Coverage assessment

At liquidation values, the collateral package provides coverage of 1.05× relative to the EUR 550,000 loan principal. At nominal values, coverage is 1.18×. Coverage is adequate but not excessive, which is consistent with the nature of the transaction: the primary source of loan repayment is the contracted cash flow from the Georgia contracts and the company’s ongoing operations, while the collateral provides tangible downside protection. As the buyer settles instalments, Capacity’s cash position improves (reducing effective loan exposure), and fully paid vehicles are released from encumbrance. In the event of buyer default, the registered liens give the lender priority enforcement rights over the remaining vehicles.

Capacity Co was foundedNov 27, 2023
Start of active work/productionDec 1, 2023
Min target10,000 USDC
Investors63
Interest paymentsmonthly
Principal repaymentsbullet
Total payments9 months

Details

Capacity’s financial track record covers two completed fiscal years: 2024 (statutory accounts audited under Korean Standards on Auditing) and 2025 (management accounts, subject to final statutory closure). Total equity as at the end of 2025 is EUR 174,275, comprising registered capital (EUR 1,333), the owner’s additional contribution (EUR 78,000), retained earnings from 2024 (EUR 11,368) and net income for 2025 (EUR 83,574). The company has not used external debt financing to date.

Historical financial performance (2024–2025)

Income statement (EUR)

Indicator

2024

2025

Revenue

684,124

1,202,341

COGS

536,432

914,768

Gross profit

147,692

287,573

OPEX

131,240

189,470

Operating profit

16,452

98,103

Financial expenses

3,821

5,346

Profit before taxes

12,631

92,757

Income taxes

1,263

9,183

Net profit

11,368

83,574


Margin and growth indicators

Indicator

2024

2025

YoY revenue growth (%)

—

75.8%

YoY gross profit growth (%)

—

94.7%

YoY net profit growth (%)

—

635.2%

Gross profit margin (%)

21.6%

23.9%

Operating profit margin (%)

2.4%

8.2%

Net profit margin (%)

1.7%

7.0%

Interpretation of historical dynamics

Revenue increased from EUR 684k in 2024 to EUR 1.2m in 2025 (+75.8%). The 2024 figure reflects the first full operating year, during which the primary focus was on supplier onboarding and export workflow development. The 2025 result represents the transition to active scaling, with materially higher shipment volumes across multiple markets.

Gross profit nearly doubled from EUR 148k to EUR 288k (+94.7%), with the gross margin improving from 21.6% to 23.9% as the COGS-to-revenue ratio declined from 78.4% to 76.1%, indicating improved procurement efficiency at higher volumes. Net profit increased from EUR 11k to EUR 84k, with net margin improving from 1.7% to 7.0%. The cost structure shows clear operating leverage: OPEX grew by 44.3% while revenue grew by 75.8%, compressing the OPEX-to-revenue ratio from 19.2% to 15.8%. Financial expenses remained minimal (EUR 3.8k and EUR 5.3k) in both years, reflecting the absence of external debt.

Forecast financial performance (2026–2027)

The projections incorporate the Georgia EV contracts described in the Growth Plan chapter and interest expenses on the planned EUR 550k facility — the company’s first external borrowing.

Projected income statement (EUR)

Indicator

2026 (F)

2027 (F)

Revenue

1,666,523

1,770,485

COGS

1,252,932

1,335,202

Gross profit

413,591

435,283

OPEX

236,837

248,221

Operating profit

176,754

187,062

Interest expenses

45,917

40,479

Profit before taxes

130,837

146,583

Income tax

12,953

16,006

Net profit

117,884

130,577


Projected margin and growth indicators

Indicator

2026 (F)

2027 (F)

YoY revenue growth (%)

38.6%

6.2%

YoY gross profit growth (%)

43.8%

5.2%

YoY net profit growth (%)

41.1%

10.8%

Gross profit margin (%)

24.8%

24.6%

Operating profit margin (%)

10.6%

10.6%

Net profit margin (%)

7.1%

7.4%


Revenue is projected at EUR 1.67m in 2026 (+38.6%), driven by the Georgia EV contracts (combined contract value EUR 800k) and continued expansion of the core export business. The 2027 projection of EUR 1.77m (+6.2%) reflects moderation as the Georgia contracts move into final settlement, with the base business continuing at a steady pace. Gross margin stabilises at approximately 24.8–24.6%.

Operating leverage continues to strengthen: the OPEX-to-revenue ratio declines from 15.8% in 2025 to 14.2% in 2026 and 14.0% in 2027, as the fixed and semi-fixed cost base absorbs higher volumes without proportional growth. Operating profit reaches EUR 177k in 2026 and EUR 187k in 2027.

The most significant structural change is the introduction of external debt financing. Interest expenses rise from EUR 5.3k in 2025 to EUR 45.9k in 2026 and EUR 40.5k in 2027 — an approximately 8.6× increase. The ratio of operating profit to interest expense is 3.9× in 2026 and 4.6× in 2027, well above the 1.5× minimum threshold for basic debt serviceability. Net profit is projected at EUR 118k in 2026 and EUR 131k in 2027, with net margin stable at 7.1–7.4%. Projected 2026 net income alone would add approximately 68% to the current equity base.

Growth Plan of Capacity Co., Ltd.

Beyond the continued development of its core spare parts and used vehicle business across Central Asia and the Middle East, Capacity’s growth plan for 2026 centres on a specific expansion opportunity: the export of Korean electric vehicles to Georgia under a structured two-contract arrangement with LLC Automoby (registration number 446977022, Georgia), an existing commercial counterparty with prior transaction history. Preliminary agreements have been concluded; the contracts are expected to be finalised upon securing external financing. The project uses the company's existing procurement channels and port infrastructure but represents a step-change in average transaction size and introduces electric vehicles as a new product category, while deepening the company's presence in an existing but underutilised export market.

Counterparty and commercial structure

In February 2026, Capacity entered into a preliminary agreement with LLC Automoby for the supply of Korean electric vehicles. The end user of the vehicles is DW AUTO LLC, a Georgian vehicle rental operator expanding its fleet; Automoby acts as the procurement intermediary. The arrangement is structured as two separate contracts, each for a batch of ten vehicles, to be executed sequentially — the second commencing approximately two months after the first shipment is dispatched. Both contracts will be finalised and vehicle procurement will commence upon receipt of external financing.

Contract 1 — Genesis G80 Electrified

The first contract provides for the supply of ten Genesis G80 Electrified vehicles, model years 2023–2024, to be sourced in the Korean wholesale market at an average procurement cost of EUR 35,000 per unit. Delivery is to be arranged on CIF Batumi terms (cost, insurance and freight borne by Capacity), from the port of Busan to the port of Batumi (Georgia). The shipping route runs via the Cape of Good Hope rather than through the Suez Canal, reflecting the ongoing disruption to Red Sea shipping lanes; estimated sea transit is up to three months. The logistics cost includes cargo insurance for the full transit period.

The contract timeline is approximately 11 months from contract finalisation to receipt of the final payment: up to two months for financing, vehicle procurement, pre-sale preparation and export documentation; up to three months for sea transit; and six months of post-delivery instalment payments by the buyer.

Payment terms: 10% advance upon contract finalisation (EUR 47,250); 40% upon receipt of shipping documentation after dispatch (EUR 189,000); remaining 50% in six equal monthly instalments after delivery in Batumi (EUR 236,250 total, approximately EUR 39,375 per month). Total contract value: EUR 472,500.

Contract 2 — Hyundai Ioniq 5

The second contract provides for the supply of ten Hyundai Ioniq 5 vehicles, model years 2022–2023, to be sourced through the same Korean wholesale channels at an average procurement cost of EUR 24,000 per unit. Delivery terms (CIF Batumi), shipping route and logistics arrangements are identical to Contract 1. The overall cycle follows the same structure and approximate duration.

Payment terms: 20% advance (EUR 65,580); 50% upon receipt of shipping documentation (EUR 163,950); remaining 30% in six monthly instalments after delivery (EUR 98,370 total, approximately EUR 16,395 per month). Total contract value: EUR 327,900.

Under both contracts, Capacity provides a 12-month warranty on all supplied vehicles, reflected in the contract pricing. The warranty exposure is partially mitigated by the relatively recent model years (2022–2024), which fall within or close to the manufacturers’ original warranty periods (typically five years for Hyundai and Genesis vehicles, including high-voltage battery and drivetrain components).

Contract economics

Cost and revenue structure (EUR)

Item

Genesis G80 Electrified

Hyundai Ioniq 5

Average procurement cost per vehicle

35,000

24,000

Number of vehicles

10

10

Total procurement cost in Korea

350,000

240,000

Logistics (Busan–Batumi)

19,000

19,000

Customs clearance in Georgia (maximum)

2,000

2,000

Total cost to Capacity

371,000

261,000

Contract value to buyer

472,500

327,900

Trading margin (contract value less cost)

101,500

66,900

Trading margin (%)

21.5%

20.4%


VAT refund and total margin (EUR)

Item

Genesis G80 Electrified

Hyundai Ioniq 5

Korean VAT refund on export (procurement cost / 11)

~32,000

~22,000

Total margin including VAT refund

133,500

88,900

Total margin including VAT refund (%)

28.3%

27.1%


The trading margin of 21.5% (Contract 1) and 20.4% (Contract 2) is within the company’s typical vehicle export range (15–21%). The additional margin component comes from the Korean VAT refund: domestic prices include 10% VAT, recoverable upon export (calculated as the procurement cost divided by 11). With this refund, the effective margin rises to 28.3% and 27.1% respectively.

Three structural factors support the margin on these contracts. The company plans to source part of the vehicle batch directly from fleet operators and leasing companies in Korea, which provides access to volume-based pricing below standard auction levels. Import duties and excise taxes on electric vehicles in Georgia are currently zero, which eliminates an expense line that would otherwise compress the buyer’s willingness to pay. The Korean VAT refund mechanism on EV exports is a standard fiscal instrument available to all qualifying exporters.

The combined contract value is EUR 800,400. Total cost to Capacity is EUR 632,000. The combined gross margin including VAT refund is EUR 222,400, representing a blended margin of ~27.8%. The majority of client payments are expected to be received within 2026.

Financing rationale

The total cost of executing both contracts is EUR 632,000. Client advance payments total EUR 112,830 (EUR 47,250 under Contract 1 and EUR 65,580 under Contract 2), reducing the net amount to be pre-financed to approximately EUR 519,000.

The company plans to attract external financing of EUR 550,000. The difference between the net financing need (EUR 519,000) and the requested facility amount provides a liquidity buffer of approximately EUR 31,000 (~4.9% of total cost). Given the three-month logistics cycle via the Cape of Good Hope and the exposure to price fluctuations in the Korean used EV market during the procurement phase, this buffer is sized as a minimum operational reserve rather than a comprehensive risk cushion. Any material cost overrun beyond this buffer would need to be absorbed from the company’s ongoing cash flow from standard operations.

Without external financing, execution of the Georgia contracts would require diverting substantially all of the company’s available working capital, making it unable to continue its standard spare parts and used vehicle orders in parallel. The external facility is therefore required both to fund the Georgia contracts and to preserve the company’s ongoing operational capacity.

Description of the Loan

Facility overview and purpose

Capacity requests a short-term working capital facility of EUR 550,000 to finance the execution of the two Georgia electric vehicle export contracts described in the Growth Plan chapter. The loan is designed to bridge the gap between upfront procurement and logistics costs and the staged client payments received over a period of up to 11 months per contract. The facility is project-linked and is not intended to refinance historical obligations or cover operating losses.

Use of proceeds and tranche structure

The facility is divided into two tranches aligned with the sequential execution of the two contracts:

  • Tranche 1 — EUR 350,000: procurement of the first vehicle batch (Genesis G80 Electrified), export logistics and a portion of the contingency buffer.
  • Tranche 2 — EUR 200,000: procurement of the second vehicle batch (Hyundai Ioniq 5), export logistics and the remainder of the contingency buffer.

Tranche 1 is drawn at commencement of the project. Tranche 2 is drawn approximately two months after dispatch of the first shipment, corresponding to the planned start of procurement for the second contract. The staggered drawdown reduces the period during which the full facility amount is outstanding and aligns financing costs with actual capital deployment.

Repayment terms

Parameter

Value

Total loan amount

EUR 550,000

Number of tranches

2

Interest rate

22.1% per annum (fixed)

Period

9 months

Debt service

Monthly interest-only payments on outstanding principal

Principal repayment

Bullet repayment at maturity per tranche

Total interest cost

EUR 91,162

Total repayment (principal + interest)

EUR 641,162


Risk scoring

Total risk scoreBBB
Debt to equity3.16
LTV95%
Credit history8 / 10
Collateral typeCompany Assets

Rating BBB (the fourth tier) reflects a young but profitable exporter: founded in late 2023 on the owner’s own money, it grew revenue from €684k in 2024 to €1.2M in 2025 and has used no external debt to date.

  • D/E (Debt-to-equity) of 3.16 is high, as equity is still small — €174,275 at the end of 2025;
  • LTV of 95% means collateral at liquidation value covers the €550k facility about 1.05 times;
  • Credit history score of 8/10.

Keep in mind:

  • the Georgia contracts are preliminary agreements, to be finalised once financing is secured;
  • strategy and key client relationships rest with the owner, a key-person dependency;
  • several anchor buyers account for a significant share of revenue, with no long-term supply agreements;
  • sea transit takes up to three months, and the ~€31,000 buffer is only a minimum reserve.

Key risks and mitigants

Strategic and commercial functions remain concentrated in a single individual — a structural key-person dependency characteristic of the company’s current stage. The client base is relatively concentrated, with several anchor buyers accounting for a significant share of revenue.

The Georgia project is a step-change in average transaction size and introduces electric vehicles as a new product category. Preliminary agreements have been concluded, and the contracts are expected to be finalised upon securing external financing. Given the three-month sea transit via the Cape of Good Hope and exposure to price fluctuations in the Korean used EV market during procurement, the liquidity buffer of approximately EUR 31,000 is sized as a minimum operational reserve rather than a comprehensive risk cushion; a material cost overrun beyond it would have to be absorbed from the cash flow of standard operations.

Capacity provides a 12-month warranty on all supplied vehicles, reflected in the contract pricing. The exposure is partly mitigated by the recent model years (2022–2024), within or close to the manufacturers’ original warranty periods — typically five years for Hyundai and Genesis, including the high-voltage battery and drivetrain.

Financials

Revenue 2025€1.2M
Net profit 2025€84k
Gross margin 202523.9%
Interest cover3.9×
€ thousands
€684k684
+76%€1202k1202
+39%€1667k*1667*
+6%€1770k*1770*
202420252026F2027F

* 2026–2027 are management forecasts including the Georgia EV contracts and interest on the €550k facility; 2025 is management accounts
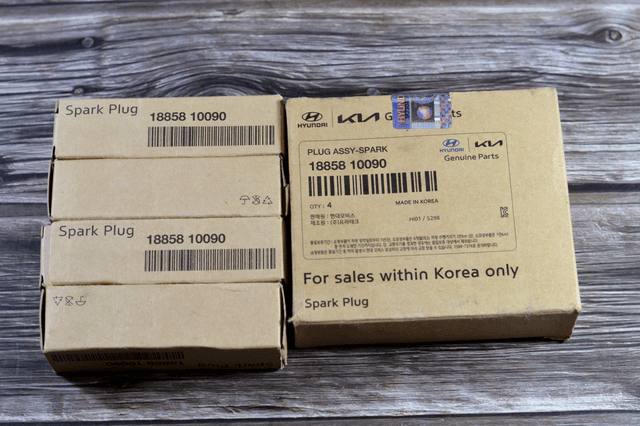
Korean Parts

Capacity grew fast in its first two full years. The 2026 forecast adds the Georgia EV contracts on top of the core parts and used-car business.

Fast revenue growth

  • Revenue rose 75.8%, from €684k in 2024 to €1.2M in 2025.
  • The forecast is €1.67M in 2026 (+38.6%) and €1.77M in 2027 (+6.2%), as the Georgia contracts settle.

Improving profitability

  • Gross margin improved from 21.6% to 23.9% as procurement became more efficient at higher volumes.
  • Net profit rose from €11k to €84k; the forecast is €118k in 2026 and €131k in 2027.

Operating leverage and debt service

  • OPEX grew 44.3% against 75.8% revenue growth, cutting OPEX to revenue from 19.2% to 15.8%.
  • Interest rises to €45.9k in 2026, but operating profit covers it 3.9× in 2026 and 4.6× in 2027 — well above the 1.5× minimum.

Market

South Korea exported $22.55bn of car parts in 2024, anchored by the Hyundai Motor Group ecosystem, and about 639,000 used vehicles in 2023. Central Asia and the Middle East favour Korean models; in Kazakhstan, the region’s largest market, Hyundai and Kia hold about 32% of new-car sales. Key risks are Chinese aftermarket competition, destination-market tariffs and shipping disruption.

Historical financial performance

The track record covers two completed fiscal years: 2024 (statutory accounts audited under Korean Standards on Auditing) and 2025 (management accounts, subject to final statutory closure). Total equity at the end of 2025 is EUR 174,275: registered capital (EUR 1,333), the owner’s additional contribution (EUR 78,000), retained earnings from 2024 (EUR 11,368) and net income for 2025 (EUR 83,574). The company has not used external debt financing to date.

Income statement, EUR

Indicator20242025
Revenue684,1241,202,341
COGS536,432914,768
Gross profit147,692287,573
OPEX131,240189,470
Operating profit16,45298,103
Financial expenses3,8215,346
Profit before taxes12,63192,757
Income taxes1,2639,183
Net profit11,36883,574

Margin and growth indicators

Indicator20242025
YoY revenue growth—75.8%
YoY gross profit growth—94.7%
YoY net profit growth—635.2%
Gross profit margin21.6%23.9%
Operating profit margin2.4%8.2%
Net profit margin1.7%7.0%

The 2024 figure reflects the first full operating year, focused on supplier onboarding and export workflow development; 2025 marks the transition to active scaling, with materially higher shipment volumes across multiple markets. Gross profit nearly doubled from EUR 148k to EUR 288k (+94.7%) as the COGS-to-revenue ratio declined from 78.4% to 76.1%, indicating improved procurement efficiency at higher volumes. Net margin improved from 1.7% to 7.0%. Financial expenses remained minimal (EUR 3.8k and EUR 5.3k), reflecting the absence of external debt.

Forecast 2026F–2027F

The projections incorporate the Georgia EV contracts and interest on the planned EUR 550k facility — the company’s first external borrowing.

Projected income statement, EUR

Indicator2026F2027F
Revenue1,666,5231,770,485
COGS1,252,9321,335,202
Gross profit413,591435,283
OPEX236,837248,221
Operating profit176,754187,062
Interest expenses45,91740,479
Profit before taxes130,837146,583
Income tax12,95316,006
Net profit117,884130,577

Projected margin and growth indicators

Indicator2026F2027F
YoY revenue growth38.6%6.2%
YoY gross profit growth43.8%5.2%
YoY net profit growth41.1%10.8%
Gross profit margin24.8%24.6%
Operating profit margin10.6%10.6%
Net profit margin7.1%7.4%

Revenue of EUR 1.67m in 2026 is driven by the Georgia EV contracts (combined contract value EUR 800k) and continued expansion of the core export business; the 2027 projection of EUR 1.77m reflects moderation as the Georgia contracts move into final settlement. Operating leverage continues to strengthen: the OPEX-to-revenue ratio declines from 15.8% in 2025 to 14.2% in 2026 and 14.0% in 2027, and operating profit reaches EUR 177k and EUR 187k.

The most significant structural change is external debt. Interest expenses rise from EUR 5.3k in 2025 to EUR 45.9k in 2026 and EUR 40.5k in 2027 — an approximately 8.6× increase. Operating profit covers interest 3.9× in 2026 and 4.6× in 2027, well above the 1.5× minimum threshold for basic debt serviceability. Net profit is projected at EUR 118k in 2026 and EUR 131k in 2027; projected 2026 net income alone would add approximately 68% to the current equity base.

Growth plan: the Georgia EV contracts

Beyond the core spare parts and used vehicle business across Central Asia and the Middle East, the 2026 growth plan centres on exporting Korean electric vehicles to Georgia under a two-contract arrangement with LLC Automoby (registration number 446977022, Georgia), an existing counterparty with prior transaction history. The end user is DW AUTO LLC, a Georgian vehicle rental operator expanding its fleet; Automoby acts as the procurement intermediary. The preliminary agreement was entered into in February 2026. The project uses the existing procurement channels and port infrastructure and deepens the company’s presence in an existing but underutilised export market.

The two contracts of ten vehicles each run sequentially, the second starting approximately two months after the first shipment is dispatched. Delivery is CIF Batumi — cost, insurance and freight borne by Capacity — from Busan to Batumi via the Cape of Good Hope rather than the Suez Canal, reflecting the ongoing disruption to Red Sea shipping; estimated sea transit is up to three months, with cargo insurance for the full period. Each contract runs approximately 11 months from finalisation to final payment: up to two months for financing, procurement, pre-sale preparation and export documentation, up to three months at sea, and six months of post-delivery instalments.

TermContract 1 — Genesis G80 ElectrifiedContract 2 — Hyundai Ioniq 5
Vehicles10 units, model years 2023–202410 units, model years 2022–2023
Average procurement costEUR 35,000 per unitEUR 24,000 per unit
Advance10% on contract finalisation (EUR 47,250)20% (EUR 65,580)
On shipping documents40% (EUR 189,000)50% (EUR 163,950)
Instalments after delivery50% in six equal monthly instalments (EUR 236,250, ~EUR 39,375 a month)30% in six monthly instalments (EUR 98,370, ~EUR 16,395 a month)
Total contract valueEUR 472,500EUR 327,900

Contract economics

Cost and revenue structure, EUR

ItemGenesis G80 ElectrifiedHyundai Ioniq 5
Average procurement cost per vehicle35,00024,000
Number of vehicles1010
Total procurement cost in Korea350,000240,000
Logistics (Busan–Batumi)19,00019,000
Customs clearance in Georgia (maximum)2,0002,000
Total cost to Capacity371,000261,000
Contract value to buyer472,500327,900
Trading margin101,50066,900
Trading margin, %21.5%20.4%

VAT refund and total margin, EUR

ItemGenesis G80 ElectrifiedHyundai Ioniq 5
Korean VAT refund on export (procurement cost / 11)~32,000~22,000
Total margin including VAT refund133,50088,900
Total margin including VAT refund, %28.3%27.1%

The trading margins of 21.5% and 20.4% sit within the company’s typical vehicle export range of 15–21%. The additional component is the Korean VAT refund: domestic prices include 10% VAT, recoverable on export, which lifts the effective margin to 28.3% and 27.1%. Three factors support the margin: part of the batch is to be sourced directly from fleet operators and leasing companies at volume prices below standard auction levels; import duties and excise on electric vehicles in Georgia are currently zero; and the VAT refund on EV exports is a standard fiscal instrument available to all qualifying exporters.

The combined contract value is EUR 800,400 against a total cost of EUR 632,000; the combined margin including the VAT refund is EUR 222,400, a blended ~27.8%. The majority of client payments are expected within 2026.

Market assessment

The automotive aftermarket — replacement parts and maintenance services after the original vehicle sale — is a large and structurally growing global market. Estimates for 2025 range from approximately $489bn (Grand View Research) to $860bn (Precedence Research), depending on methodology and scope, and most forecasts project 3–6% CAGR through the end of the decade. Demand is driven by a global light-vehicle fleet projected to reach approximately 1.7 billion units by 2033 (S&P Global Mobility), rising average vehicle age in mature markets (over 12.6 years in the US in 2024), and fast-growing vehicle ownership in developing economies that need affordable non-OEM and aftermarket components.

South Korea as a parts export hub

South Korean automotive parts exports reached $22.55bn in 2024 (KAICA), anchored by the Hyundai Motor Group ecosystem, including Hyundai Mobis and a network of independent OEM manufacturers. Hyundai Motor and Kia together sold 7.23 million vehicles globally in 2024, making the group the world’s third-largest automaker, and the automotive sector accounts for approximately 15% of total Korean exports. The US takes 36.5% of parts exports, the EU 17.3%, Mexico 9.5% and China 6.4%; the rest goes to the Middle East, Central Asia, Southeast Asia and Africa — the segment most relevant to Capacity.

Korean used vehicle exports

South Korea exported approximately 639,000 used vehicles in 2023 (+36% versus 2021). Korean vehicles are favoured in Middle Eastern and Central Asian markets over Japanese alternatives because they are configured for right-hand traffic, and a weaker won in 2024–2025 has further improved price competitiveness. Japan’s 2023 restrictions on used vehicle exports to Russia and South Korea’s own partial restrictions in 2024 have redirected trade flows through Central Asian intermediaries, particularly Kazakhstan and Kyrgyzstan.

Central Asia and the Middle East

Capacity’s principal markets share high Korean-brand fleet penetration, limited domestic parts manufacturing and established routes from Korean export ports. Kazakhstan, the largest automotive market in Central Asia, sold 234,852 new vehicles in 2025 (+14.4%); Hyundai holds a 21.9% share and Kia 10.0% — together approximately 32% — and the registered fleet exceeds five million units. The UAE is a regional distribution hub, with Jebel Ali port facilitating re-export across the Middle East and North Africa, while Turkey, Libya, Kyrgyzstan and Uzbekistan add structurally supported demand.

Challenges

  • Competitive pressure from Chinese aftermarket manufacturers.
  • Regulatory and tariff uncertainty in destination markets.
  • Logistics disruption, such as the Red Sea shipping disruptions of 2024.
  • The long-term transition to electric powertrains, though its timeline in the company’s emerging-market destinations remains extended.

Collateral breakdown

Contract vehicles (20 Korean EVs) · €590K
Contract vehicles (20 Korean EVs)€590,000
Existing operational assets€61,290
Total pledged€651,290Nominal values; at liquidation values the package is €580,032, or 1.05× the €550k facility.

The €550k facility is secured in two layers.

1. Twenty contract vehicles — €590,000

  • Ten Genesis G80 Electrified and ten Hyundai Ioniq 5 bought with the loan.
  • Pledged directly to the lender during procurement and transit.
  • After delivery in Batumi, the security becomes a claim on the liens registered in Georgia and on the outstanding instalments.
  • Discounted only 10% for liquidation, given the active secondary market for these model years.

2. Existing operational assets — €61,290

  • Warehouse infrastructure and handling equipment
  • Two Hyundai vehicles from 2021
  • CCTV, IT equipment and office furniture

Total collateral is €651,290 nominal and €580,032 at liquidation values — 1.18× and 1.05× the principal. Coverage is adequate rather than generous: repayment comes first from the contracted cash flow, with the pledge as downside protection.

Loan collateral

The EUR 550,000 facility is secured by a two-layer structure combining existing company-owned operational assets and the 20 electric vehicles acquired under the Georgia contracts with loan proceeds. Collateral is valued at nominal and conservative liquidation values, with liquidation discounts of 20% for existing operational assets and 10% for contract vehicles.

Collateral sourceNominal value (EUR)Liquidation value (EUR)
Existing operational assets (80%)61,29049,032
Contract vehicles / assigned rights (90%)590,000531,000
Total collateral651,290580,032
Coverage metricValue
Loan principalEUR 550,000
Total collateral (nominal)EUR 651,290
Total collateral (liquidation)EUR 580,032
Nominal coverage ratio1.18×
Liquidation coverage ratio1.05×
  • Existing operational assets — warehouse infrastructure, materials handling equipment, two vehicles (Hyundai Porter II and Hyundai Tucson, both 2021), CCTV, IT equipment and office furniture, at aggregate book value.
  • Contract vehicles — ten Genesis G80 Electrified and ten Hyundai Ioniq 5, the principal layer. During procurement and transit they are pledged directly to the lender. After delivery in Batumi they pass to the buyer on instalment terms with a registered lien in favour of Capacity, recorded in the National Agency of Public Registry of Georgia, and the lender’s security becomes a claim on Capacity’s enforceable contractual rights, including the registered liens and the outstanding instalments.
  • The 90% liquidation rate on contract vehicles reflects the active secondary market for Korean electric vehicles of the 2022–2024 model years.

Coverage is adequate but not excessive, consistent with the nature of the transaction: the primary repayment source is the contracted cash flow from the Georgia contracts and ongoing operations, with the collateral as tangible downside protection. As the buyer settles instalments, Capacity’s cash position improves and fully paid vehicles are released from encumbrance; in a buyer default, the registered liens give the lender priority enforcement rights over the remaining vehicles.

Financing rationale

Executing both contracts costs EUR 632,000. Client advances total EUR 112,830 (EUR 47,250 under Contract 1 and EUR 65,580 under Contract 2), reducing the amount to be pre-financed to approximately EUR 519,000. The EUR 550,000 facility leaves a liquidity buffer of approximately EUR 31,000, ~4.9% of total cost.

Without external financing, executing the Georgia contracts would divert substantially all of the company’s available working capital and stop it from running standard spare parts and used vehicle orders in parallel. The facility therefore both funds the contracts and preserves the company’s ongoing operating capacity.

Description of the loan

Capacity requests a short-term working capital facility of EUR 550,000 to finance the two Georgia EV export contracts, bridging upfront procurement and logistics costs and the staged client payments received over up to 11 months per contract. The facility is project-linked and is not intended to refinance historical obligations or cover operating losses.

Tranche structure

  • Tranche 1 — EUR 350,000: procurement of the first batch (Genesis G80 Electrified), export logistics and part of the contingency buffer; drawn at the start of the project.
  • Tranche 2 — EUR 200,000: procurement of the second batch (Hyundai Ioniq 5), export logistics and the rest of the buffer; drawn approximately two months after dispatch of the first shipment.

The staggered drawdown shortens the period during which the full amount is outstanding and aligns financing costs with actual capital deployment.

Repayment terms

ParameterValue
Total loan amountEUR 550,000
Number of tranches2
Interest rate22.1% per annum (fixed)
Period9 months
Debt serviceMonthly interest-only payments on outstanding principal
Principal repaymentBullet repayment at maturity per tranche
Total interest costEUR 91,162
Total repayment (principal + interest)EUR 641,162

Borrower

Capacity CoGyeonggi-do, South Korea · founded 2023
Capacity Co

Capacity Co., Ltd. is a South Korea–based B2B export trading company specialising in the wholesale export of Korean automotive spare parts (genuine, OEM and aftermarket components for Hyundai, Kia and Genesis vehicles) and used Korean-manufactured automobiles. The company operates as a trading principal and export consolidator: it sources products from Korean manufacturers and authorised distributors, aggregates orders for overseas buyers, performs quality control and packaging, and coordinates export logistics through the ports of Pyeongtaek and Busan. The company is based in Pyeongtaek, Gyeonggi Province — in direct proximity to tier-one Korean parts suppliers and major export terminals.

Reg No: 239-86-02819www.nexkoreatrade.com

About the company

Capacity Co., Ltd. is a South Korea–based B2B export trading company specialising in the wholesale export of Korean automotive spare parts — genuine, OEM and aftermarket components for Hyundai, Kia and Genesis vehicles — and used Korean-manufactured automobiles. It sources products from Korean manufacturers and authorised distributors, aggregates orders for overseas buyers, performs quality control and packaging, and coordinates export logistics through the ports of Pyeongtaek and Busan. The company is based in Pyeongtaek, Gyeonggi Province, in direct proximity to tier-one Korean parts suppliers and major export terminals.

Both lines serve the same B2B client base and use the same logistics infrastructure. The spare parts portfolio covers three sourcing tiers — genuine parts via Hyundai Mobis and official channels, OEM components and aftermarket alternatives — with gross margins of 20–28%. Used vehicles are sourced through Korean wholesale auctions and leasing companies, with margins of 15–21%. The blended gross margin across both lines is approximately 22–24%.

Corporate identifiers: Capacity Co., Ltd.; registration number 239-86-02819; established 27 November 2023; registered office Rm. 201, 28-11, Yeosul 4-gil, Poseung-eup, Pyeongtaek-si, Gyeonggi-do 17955, South Korea.

Operating model and clients

The operating model is order-driven and asset-light: procurement is performed against confirmed customer orders, which limits inventory risk. The cycle begins with a customer advance of typically 30–50% of order value, followed by procurement, inspection, packaging and export shipment. Suppliers are paid in full at procurement, while customers settle the balance after receiving the shipping documentation, creating a working capital gap of 20–60 days per transaction. Scalability is therefore linked primarily to working capital rather than to fixed infrastructure.

The start-up was funded with registered capital of EUR 1,333 plus a personal contribution of EUR 78,000 invested during 2023–2024, with no external debt. Besides the five principal markets, the company has secondary activity in Uzbekistan and Georgia. Client relationships develop through trial orders followed by increasing volumes; the company does not operate under long-term supply agreements.

Accounting, tax reporting and customs brokerage are outsourced, and the existing warehouse and logistics setup does not constrain moderate growth.

Ownership and management

Capacity is solely owned and managed by Ten Andrey Vladimirovich (born 1978), director and sole shareholder. Before founding the company he spent over 15 years in the automotive industry: first as co-owner and operational manager of an automotive service centre, then in a senior management position at a dealership responsible for commercial operations, inventory management and supplier coordination — hands-on knowledge of vehicle sourcing, parts procurement, B2B pricing and logistics.

Within Capacity, the CEO is directly responsible for all strategic decisions, key client negotiations, vehicle procurement at Korean wholesale auctions and financial oversight. The procurement and client manager handles day-to-day order execution independently, and operational processes are documented.

Fundedon Jun 23, 2026
18,481.10USDC
92.41% of 20,000 USDC
Funded date
Jun 23, 2026
Loan period
9 months
Annual interest
22.10 %

Fundraising is closed. Positions in this deal can be bought from other investors on the Secondary market.